Your firm’s headline EBITDA is a dangerously incomplete metric; true financial health and valuation are dictated by granular, project-level performance that lenders now scrutinise.
- Ignoring profitability on individual projects actively distorts your company’s overall valuation, regardless of total revenue.
- Lenders prioritise Adjusted EBITDA because it reflects operational cash flow, which is a more reliable indicator of your ability to service debt than Net Income.
Recommendation: Immediately implement systems for real-time tracking of material cost variances and subcontractor expenses at the project level to gain genuine financial foresight.
For any Commercial Director or CFO in the UK construction sector, the obsession with EBITDA is understandable. It has long been the headline metric for health and valuation. Yet, in an environment of razor-thin margins, volatile material costs, and intense scrutiny from lenders, relying on a company-wide, backward-looking EBITDA figure is like driving a haul truck by only looking in the rearview mirror. You see the road you’ve covered, but you have no visibility on the cliff edge directly ahead. The market is littered with firms that posted impressive-looking quarterly earnings right before collapsing under the weight of a few disastrous projects.
The standard advice— »track your KPIs, » « control costs »—is no longer sufficient. These are platitudes that ignore the operational realities of a busy site. The real challenge is embedding financial discipline at the source of value and cost: the project itself. This requires a shift in mindset from historical accounting to proactive, real-time financial foresight. It’s about knowing your precise margin on Project X *today*, not in three months when the accounts are finalised. It means understanding how seemingly minor operational choices impact the metrics that lenders and potential buyers truly care about.
But if the answer isn’t just staring at your top-line EBITDA, what is? The key lies in dissecting your profitability, understanding the metrics that UK lenders genuinely trust, and identifying the hidden financial drains before they cripple your working capital. This is not about more accounting; it’s about more intelligent, granular control that directly influences your firm’s valuation and its access to capital.
This article will dissect the advanced financial strategies required to navigate the modern construction landscape. We will move beyond generic advice to provide a clear framework for protecting margins, satisfying lenders, and building a more resilient and valuable construction business.
Summary: Advanced EBITDA Monitoring Strategies for UK Construction Firms
- Why Ignoring Project-Level Profitability Skews Overall Construction Valuations?
- How to Track Material Cost Variances Without Delaying Site Operations?
- Adjusted EBITDA vs Net Income: Which Metric Do UK Lenders Trust More?
- The Revenue Recognition Flaw That Inflates Quarterly Earnings Artificially
- Identifying and Eliminating Hidden Subcontractor Fees That Erode Margins
- Why Delaying Sustainability Disclosures Will Restrict Your Access to Bank Capital?
- The Bulk Buying Mistake That Results in Massive Seasonal Markdowns
- Reducing Stockholding Costs to Free Up Working Capital in UK Retail
Why Ignoring Project-Level Profitability Skews Overall Construction Valuations?
A construction firm’s valuation is not a simple average of its activities; it’s a risk assessment. Lenders and acquirers are laser-focused on the quality and predictability of earnings. A company with ten profitable projects and one that is haemorrhaging cash is viewed as a higher risk than a company with eight consistently profitable projects, even if their total EBITDA is identical. The single bad project signals a lack of control, a systemic weakness that could replicate itself and jeopardise future performance. This is where company-wide EBITDA becomes a vanity metric, masking underlying instability that directly suppresses valuation multiples.
This isn’t theoretical. The market actively rewards specialisation and predictable margins. For instance, an analysis of the M&A market shows how project-level focus directly impacts company valuations. It highlights that HVAC businesses focused on new construction might trade at 4x EBITDA, while those with a significant, predictable service and replacement component can command multiples of 6x EBITDA. The difference is the perceived risk and margin stability. The service component provides a reliable, repeatable revenue stream, which is valued far more highly than the boom-and-bust cycle of large-scale, one-off projects.
Therefore, a lack of project-level granularity in your financial reporting means you are unable to demonstrate this stability. You cannot isolate and showcase your high-margin, low-risk work. Instead, it all gets blended into a single, less attractive number. Top-tier valuations of 7x to 8x EBITDA are reserved for « premium quality businesses » that can prove, project by project, that they have robust financial controls and predictable outcomes. Ignoring project-level profitability isn’t just bad accounting; it’s a direct impediment to achieving your firm’s maximum valuation.
How to Track Material Cost Variances Without Delaying Site Operations?
The greatest barrier to implementing granular financial control is operational drag. Site managers are measured on progress, not paperwork. Any system that requires them to down tools and spend an hour in a porta-cabin inputting data is doomed to fail. The solution is not more administration, but smarter, integrated technology that captures data at the point of activity. Tracking material cost variances—the difference between what you budgeted and what you actually paid—must happen in real-time, not weeks later when the invoices are processed.
This means equipping your site foremen with ruggedized tablets or mobile devices linked directly to your procurement and accounting systems. When a delivery of plasterboard arrives, the foreman scans the delivery note. The system immediately cross-references the quantity and price against the purchase order. Any discrepancy—a short delivery, a price surcharge—is flagged instantly. This allows the commercial team to challenge the supplier immediately, not a month later when the trail is cold. This is about turning a passive administrative task into an active, real-time cost control measure.
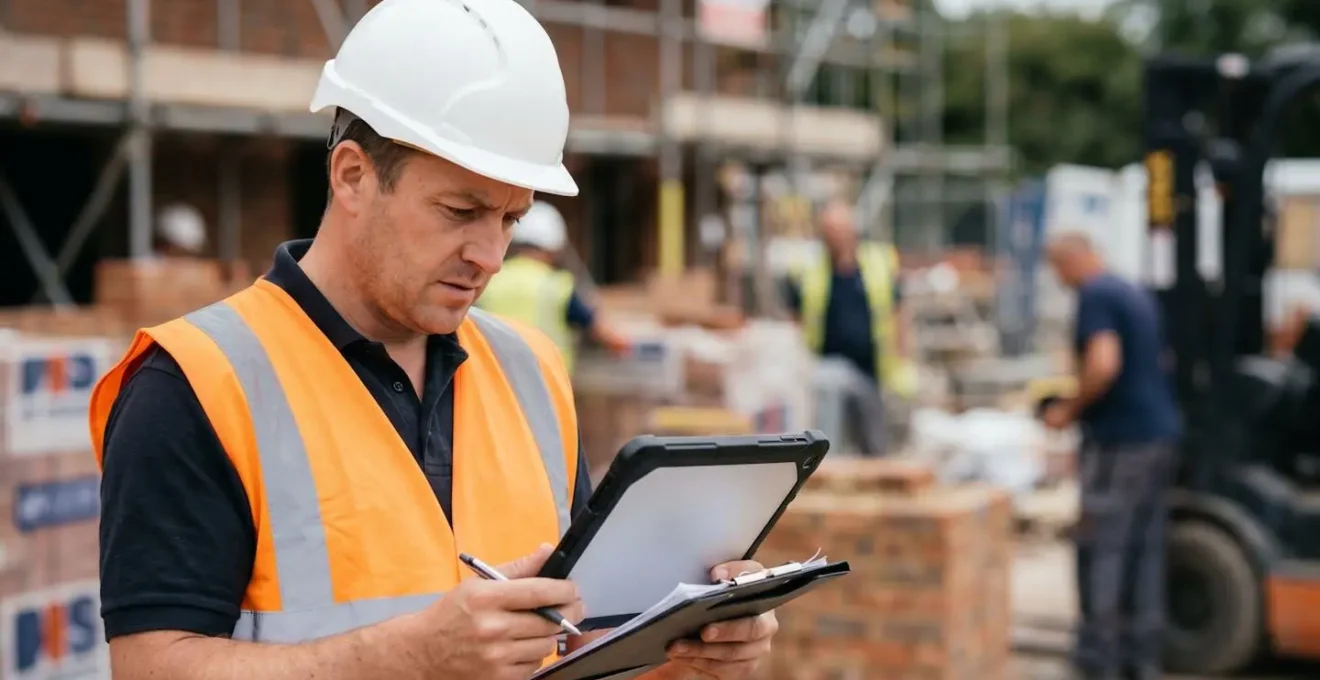
As this image illustrates, the technology exists to make this seamless. The foreman isn’t doing data entry; they are simply confirming a delivery, a task they already perform. The key is that this simple action triggers a cascade of financial verification in the background. By embedding the tracking mechanism into existing operational workflows, you gather critical variance data without causing operational drag. This provides the commercial director with a live dashboard of material cost exposure across all projects, enabling financial foresight rather than historical reaction.
Adjusted EBITDA vs Net Income: Which Metric Do UK Lenders Trust More?
When seeking finance, it’s crucial to speak the lender’s language. While Net Income is the final « bottom line, » lenders in the UK construction sector place far greater trust in Adjusted EBITDA. The reason is simple: it provides a clearer picture of a company’s operational cash-generating ability, which is what ultimately determines its capacity to service debt. Net Income can be distorted by non-cash expenses like depreciation and amortisation, as well as financing costs (interest) and taxes, which can vary wildly based on a company’s capital structure and accounting policies.
Adjusted EBITDA strips these variables out, allowing for a more direct, apples-to-apples comparison of operational performance between different companies. Lenders use it as the foundation for critical debt covenants, most notably the Debt/EBITDA ratio. This metric is a primary indicator of leverage and risk. In the US, for example, industry benchmarking data reveals a median EV/EBITDA multiple of 12.4x, showing just how central this metric is to valuation and financial analysis. UK lenders follow a similar logic, viewing a strong and stable Adjusted EBITDA as proof of a resilient business model capable of weathering economic cycles.
The following table, based on principles outlined by financial software experts, clarifies why lenders lean so heavily on this metric. As a leading industry voice, Foundation Software notes:
EBITDA provides a starting point for cash flow projections, offering a more accurate way to model company performance.
– Foundation Software, 5 Key Financial Ratios for Your Construction Business
This table summarises the lender’s perspective on these key financial metrics.
| Metric | Adjusted EBITDA Focus | Net Income Focus | Lender Preference |
|---|---|---|---|
| Cash Flow Visibility | Shows operational cash generation | Includes all expenses | EBITDA preferred |
| Debt Service Coverage | Used for Debt/EBITDA ratios | Less commonly used | EBITDA standard |
| Project Comparability | Removes financing differences | Affected by capital structure | EBITDA for benchmarking |
| Quick Ratio Standard | Not directly applicable | Supports ratio calculation | Both considered |
The Revenue Recognition Flaw That Inflates Quarterly Earnings Artificially
One of the most dangerous traps in construction finance is the misapplication of revenue recognition standards, particularly IFRS 15. The principle of recognising revenue « over time » for long-term contracts is sound, but its execution is fraught with peril. The flaw lies in recognising revenue based on estimated percentage of completion without rigorous, objective verification. This can lead to a situation where a company is booking significant « paper profits » on a project that is actually behind schedule and over budget. The quarterly earnings look healthy, but the final account will reveal a major loss—a cash-flow crisis waiting to happen.
The core of the problem, as highlighted in academic reviews of the standard, is the ambiguity in determining when « control » of an asset is transferred. An analysis of IFRS 15’s adequacy notes that while the principle is accepted, industry professionals raised concerns about the difficulty in applying it to long-term contracts. If your revenue recognition is based on optimistic site manager reports rather than independently verified milestones, you are building your financial statements on a foundation of sand. This inflated view of performance can lead to disastrous capital allocation decisions, such as paying out bonuses or dividends based on profits that don’t actually exist in cash.
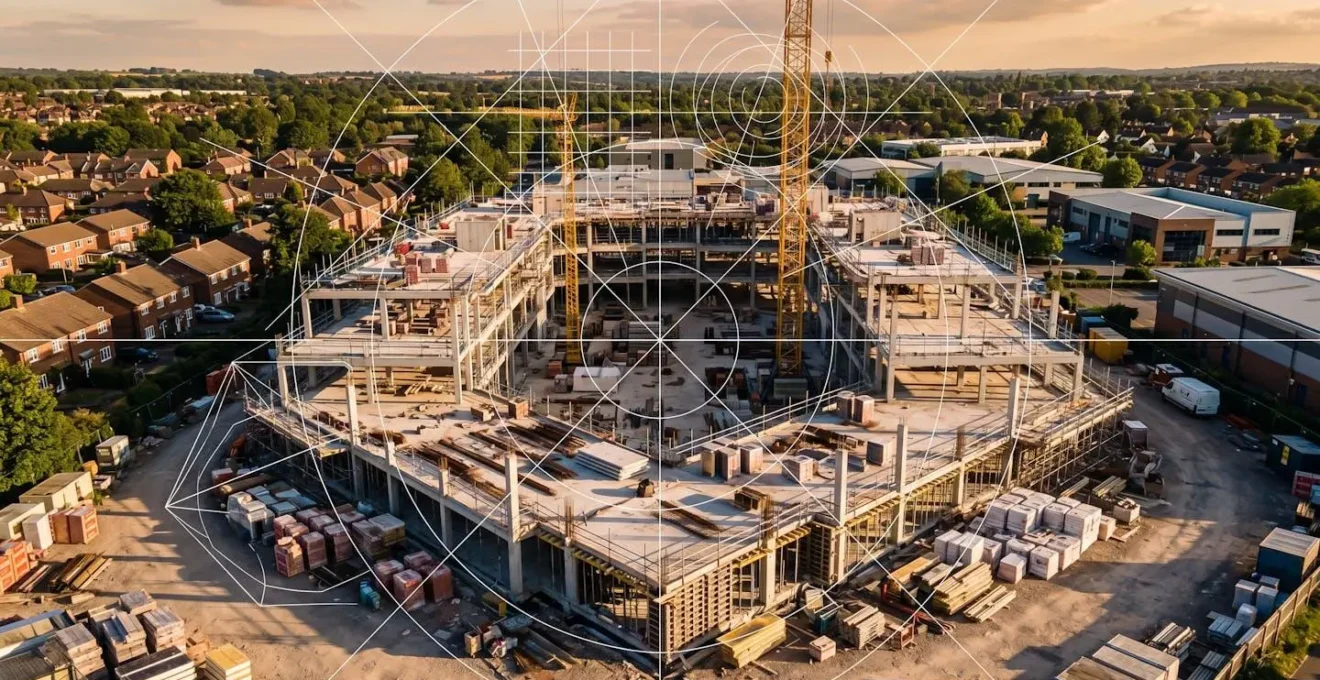
To combat this, firms must tie revenue recognition to undeniable, physically verified progress. Modern technology like drone surveying, as depicted here, allows for precise, objective measurement of work completed. By overlaying this data against the 3D model and project plan, a CFO can gain valuation integrity. You are no longer relying on opinion, but on data. This robust process not only ensures IFRS 15 compliance but also gives lenders and investors profound confidence that your reported earnings are real and backed by tangible progress on the ground.
Identifying and Eliminating Hidden Subcontractor Fees That Erode Margins
Subcontractors are the lifeblood of the UK construction industry, but unmanaged subcontractor costs are a primary source of margin erosion. The problem rarely lies in the headline contract value; it’s in the death-by-a-thousand-cuts of variations, contra-charges, day-work claims, and disputed fees that emerge during the project. A commercial director who only tracks the top-line subcontractor budget is effectively blind to the 10-15% of margin that can be silently stripped away. The difference between an average firm and a top performer often lies in the militant control of these costs.
The goal is to achieve the kind of financial performance seen at the top of the industry. For context, the CFMA’s 2024 Construction Financial Benchmarker reveals an average gross profit margin of 21.8% for the best-in-class firms. This level of profitability is impossible without a rigorous system for managing every pound spent on subcontractors. This requires a shift from a confrontational relationship to one based on transparent, data-driven accountability. Every variation must be formally instructed, costed, and approved *before* work commences. Every contra-charge for site services or remediation must be backed by photographic evidence and signed agreement.
Without this discipline, the final account negotiation becomes a chaotic, margin-destroying argument based on incomplete records. The key is to have an early warning system. By tracking subcontractor cost-to-complete on a weekly basis, you can spot overruns early and take corrective action. This isn’t about squeezing subcontractors; it’s about enforcing the commercial agreement with ruthless consistency to protect your own profitability.
Action Plan: Auditing Subcontractor Cost Controls
- Points of Contact: List all channels through which subcontractor variations and claims are submitted (email, site instructions, verbal agreements). Identify and eliminate non-formal channels immediately.
- Data Collection: Inventory all current subcontractor agreements. Are payment terms, variation procedures, and contra-charge rates explicitly defined and signed off?
- Consistency Check: Compare the process defined in your contracts with the reality on site. Are site managers approving work verbally that bypasses the formal commercial process?
- Margin Impact Analysis: On a recently completed project, analyse the difference between the initial subcontract value and the final account. Categorise every variance to identify recurring patterns of cost overrun.
- Integration Plan: Implement a mandatory digital workflow where no subcontractor payment is processed without a corresponding, approved instruction and evidence of completion. Prioritise this for your highest-value subcontractors first.
Why Delaying Sustainability Disclosures Will Restrict Your Access to Bank Capital?
For many in construction, Environmental, Social, and Governance (ESG) criteria have felt like a « soft » issue—a box-ticking exercise for corporate brochures. This is a dangerously outdated view. In the UK, ESG compliance, particularly around climate-related disclosures, has become a hard-edged financial issue. Banks and institutional lenders are no longer simply asking about your sustainability policy; they are using your ESG performance as a primary data point in their risk assessment models. Delaying or ignoring these disclosures will directly and negatively impact your ability to secure capital.
The mechanism is straightforward. As a leading law firm, Hogan Lovells, points out, « Banks now use TCFD (Task Force on Climate-related Financial Disclosures) disclosures to assess ‘climate risk’ in their loan books. » This means a construction firm with poor or non-existent disclosures is flagged as having a higher, unquantified risk profile. A higher risk profile translates directly into a higher cost of capital or, in some cases, a flat refusal to lend. This trend is accelerating, with Bartlett School of Sustainable Construction research indicating that 54% of UK Construction Law Professionals already consider ESG to be moderately to extremely important.
Conversely, proactive engagement with ESG presents a significant competitive advantage. There is a growing pool of capital specifically targeting sustainable investments. As one analysis on ESG-linked financing in the UK found, construction firms are successfully attracting funding through loan facilities with interest rates dependent on meeting specific ESG targets. This is a profound shift: good ESG performance is no longer just a reputational benefit but a direct lever to reduce your financing costs. As a CFO, ignoring ESG is tantamount to ignoring a critical variable in your cost of capital equation.
Key Takeaways
- Company-wide EBITDA is a lagging indicator; project-level margin is the true predictor of financial health.
- Lender trust is built on Adjusted EBITDA, as it reflects operational cash generation, not accounting artifacts.
- Real-time data capture on-site is non-negotiable for controlling material and subcontractor cost variances without creating operational drag.
The Bulk Buying Mistake That Results in Massive Seasonal Markdowns
The term ‘seasonal markdowns’ immediately brings retail to mind, but for a construction CFO, it has a more sinister parallel: the write-off of wasted, damaged, or stolen materials from ill-timed bulk purchases. The temptation to bulk-buy materials to get ahead of a forecasted price increase is strong. On paper, it looks like a smart commercial move. However, this strategy often backfires, creating a new set of unbudgeted costs that erode the very margin you sought to protect. This is the construction industry’s equivalent of a seasonal markdown.
Consider a bulk purchase of timber or plasterboard. Where is it stored? If it’s on a busy, partially secured site, it is vulnerable to weather damage, accidental breakage from site traffic, and theft. The « discount » you negotiated is quickly erased by the cost of materials that must be discarded and re-ordered at the new, higher price. Even if stored securely off-site, you are now incurring stockholding costs and logistical costs to transport it in smaller batches. You have traded a potential future cost for a definite present cost.
The mistake is viewing procurement as a simple transaction rather than a component of a just-in-time logistics system. The goal should be to have materials arrive on-site as close as possible to when they are needed. This minimises storage time, reduces the window for damage or theft, and improves working capital. A more sophisticated approach involves negotiating fixed-price agreements with suppliers that include phased deliveries, transferring the storage risk back to them. This may come at a slight premium, but that premium is often far less than the cost of the « markdown » on wasted materials.
Reducing Stockholding Costs to Free Up Working Capital in UK Retail
While the phrase ‘UK Retail’ might seem out of place, the underlying principle of stockholding costs is a critical, and often mismanaged, drain on working capital within the construction sector. In retail, stock that isn’t selling is dead capital. In construction, materials sitting on-site or in a yard—paid for but not yet installed and invoiced—are the exact same thing. Every pallet of bricks, every roll of insulation, and every tonne of steel represents cash that is tied up and unavailable for other critical business needs like payroll, new project bids, or subcontractor payments.
The cost is more than just the purchase price of the material. It includes storage costs (whether on-site space or a rented yard), insurance, security to prevent theft, and the financial cost of the capital itself. A firm with £1 million of excess material sitting idle has effectively reduced its available working capital by £1 million. This can be the difference between having the liquidity to seize a new opportunity and having to pass on it. It directly impacts your Working Capital Turnover ratio, a key metric of operational efficiency that lenders watch closely.
The solution, mirroring the lean inventories of successful retailers, is a relentless focus on optimising the supply chain. This means working with suppliers who can guarantee reliable, just-in-time deliveries. It involves better project planning to ensure material call-offs are accurate and timed precisely. For a CFO, a key action is to implement a system that tracks the value of materials on-site versus the project’s burn rate. If material stock exceeds the next 2-3 weeks of planned work, you have a working capital problem. Reducing this buffer frees up cash, improves financial ratios, and makes the business more agile and resilient.
The principles outlined here are not academic. They are pragmatic, numbers-driven controls required for survival and growth in the unforgiving UK construction market. The first step is to acknowledge the limitations of your current reporting and commit to achieving genuine financial foresight. Begin by auditing your most recent project’s final account against its initial budget, and the path forward will become brutally clear.