Compliance is not achieved by submitting a report; it is achieved by creating an auditable data ledger that withstands scrutiny.
- Relying on supplier estimates for Scope 3 is a direct route to report invalidation and penalties.
- Auditors now demand demonstrable ‘additionality’ for renewable energy claims, rendering generic certificates insufficient.
- Data flaws, such as double-counting between divisions or suppliers, are low-hanging fruit for HMRC investigations.
Recommendation: Shift your focus from high-level carbon accounting to establishing granular, verifiable data integrity for every emission source. This is the only path to legally defensible reporting.
As a Compliance Officer for a UK manufacturing firm, the prospect of a formal inquiry from the Financial Reporting Council or HMRC is a constant, low-level threat. The Streamlined Energy and Carbon Reporting (SECR) framework is no longer a ‘tick-box’ exercise. It is a legally binding requirement with significant financial penalties for non-compliance, and the government’s auditors are increasingly sophisticated in their investigations. Many firms believe that simply submitting numbers is enough. They are mistaken.
The common advice to « engage suppliers » or « use software » is dangerously incomplete. These are steps, not solutions. The core of compliance lies not in the final emissions total you report, but in the unimpeachable audit trail that proves how you arrived at that number. The most common compliance failures are not due to high emissions, but to poor data quality, flawed methodologies, and a fundamental misunderstanding of what auditors are trained to find. This is where firms are most vulnerable.
But what if the key to compliance was not a frantic, last-minute data scramble, but a systematic, methodical construction of a defensible data ledger? This guide departs from generic sustainability advice. It is an auditor’s perspective on building a reporting framework that anticipates scrutiny. We will not discuss vague ambitions; we will dissect the specific data failures that trigger fines and provide the precise, operational countermeasures required to ensure your reports are not just submitted, but unassailable.
This article provides a structured approach to building a robust and audit-proof emissions reporting system. The following sections will guide you through the critical areas where compliance is won or lost, from the intricacies of Scope 3 data to the subtleties of renewable energy claims.
Contents: A Framework for Defensible Emissions Reporting
- Why Relying on Supplier Estimates Invalidates Your Mandatory Scope 3 Reports?
- How to Measure Electricity Consumption Accurately Per Production Batch?
- Renewable Energy Certificates vs Direct Solar Investment: Which Satisfies Auditors?
- The Double-Counting Data Flaw That Triggers Immediate HMRC Fines
- Cutting Logistics Emissions by Redesigning Regional Delivery Routes
- How to Calculate Scope 3 Emissions Accurately Across Your Entire Supply Chain?
- Why Over-Provisioned Cloud Servers Secretly Sabotage Your Company’s Carbon Goals?
- Streamlining ESG Reporting Requirements for UK Mid-Market Manufacturers
Why Relying on Supplier Estimates Invalidates Your Mandatory Scope 3 Reports?
Scope 3 emissions, particularly from purchased goods and services, are the single largest source of reporting error and regulatory risk. Relying on spend-based estimates or unverified data from your suppliers is the equivalent of submitting a tax return based on bank statement totals without receipts. It is an invitation for auditors to invalidate your entire report. The regulatory expectation is clear: you must demonstrate a rigorous, tiered approach to data collection that prioritizes primary, activity-based data over generic industry averages.
An auditor will immediately scrutinize your methodology. If your report for a key material supplier is based on a spend-based calculation (e.g., £X spent on steel multiplied by an industry-average emissions factor), it will be flagged. This method is considered the lowest form of accuracy and is unacceptable for material emission sources. You must demonstrate a proactive effort to obtain primary data, such as the supplier’s actual energy bills, metered production line data, or audited production volumes. A report from the University of Cambridge highlights that while purchased goods are a significant emission source, reporting is often incomplete. The only defence is a clear, documented data quality framework.
Based on CDP data, Scope 3 category 1 (purchased goods and services) represents a significant portion of reported emissions, yet reporting is often incomplete with many industries omitting several Scope 3 categories.
– University of Cambridge, Understanding Industrial Scope 3 Emissions
Implementing a tiered system is the only way to demonstrate due diligence. For example, your top 20% of suppliers (representing 80% of procurement spend) must be held to a Tier 1 primary data standard. Mid-level suppliers might use a hybrid model, while spend-based estimates are relegated to only the most non-material tail-end suppliers. Without this documented stratification, your entire Scope 3 declaration lacks credibility.
How to Measure Electricity Consumption Accurately Per Production Batch?
For a manufacturer, attributing electricity consumption (Scope 2) at a company-wide level is no longer sufficient. To accurately calculate the carbon footprint of a specific product and satisfy SECR’s demand for granular data, you must measure consumption at the process, line, or even batch level. An aggregated monthly electricity bill obscures the very details an auditor will request: the energy intensity of individual products. Failure to provide this data suggests a lack of operational control and data maturity.
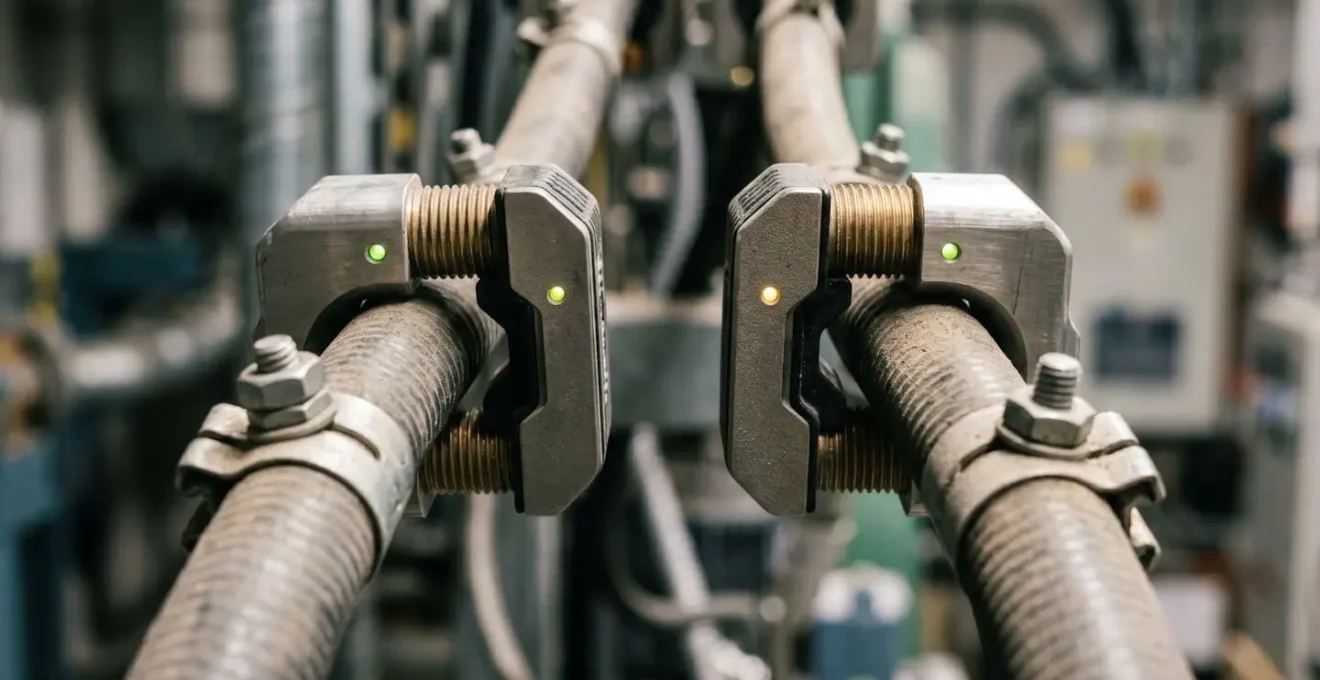
The primary method to achieve this is through sub-metering. This can be accomplished through two main approaches: integrating with existing modern factory control systems or retrofitting older equipment with non-invasive sensors. Your choice depends on your existing infrastructure, budget, and the required level of precision. Modern machines with PLC/SCADA systems can often export this data directly, offering high accuracy. For legacy equipment, non-invasive IoT current clamps are a cost-effective alternative that provides real-time data without disrupting production.
This image shows how non-invasive sensors are physically applied to equipment, providing a tangible example of the hardware required for granular data collection.
The data from these sensors allows you to create an energy profile for each production run. This enables you to not only allocate emissions accurately but also to identify inefficiencies and opportunities for reduction. An auditor will be far more satisfied with a report that states « Product A requires 15.2 kWh per unit, based on batch-level metering » than one that uses a facility-wide average. The former is a defensible fact; the latter is a guess.
This table compares the primary technologies for achieving batch-level energy tracking, providing a clear decision framework based on cost, accuracy, and compatibility. As shown by a report from Seedling.earth on manufacturing carbon footprints, these tools are essential for precise measurement.
| Technology | Installation Cost | Accuracy | Legacy Compatibility | Data Granularity |
|---|---|---|---|---|
| Non-invasive IoT Clamps | £200-500 per machine | ±2% accuracy | Excellent for pre-2000 equipment | Real-time, 1-second intervals |
| PLC/SCADA Integration | £2,000-10,000 setup | ±0.5% accuracy | Limited to post-2010 systems | Batch-specific, automated logging |
| Algorithmic Disaggregation | £5,000-15,000 model development | ±5% after training | Universal application | Predictive batch-level estimates |
Renewable Energy Certificates vs Direct Solar Investment: Which Satisfies Auditors?
Claiming your electricity is « 100% renewable » is a common marketing statement, but for SECR compliance, it is a claim that requires rigorous proof. The simple purchase of unbundled Renewable Energy Certificates (RECs) is increasingly being rejected by auditors as insufficient. The reason lies in a critical concept: additionality. An auditor must be convinced that your company’s actions led to the generation of *new* renewable energy that would not have otherwise existed. Generic RECs, which can be sourced from a wind farm built a decade ago anywhere in Europe, typically fail this test.
The UK Sustainability Reporting Standards (SRS) S2 put a specific focus on climate risks and opportunities, demanding clear evidence for any claims made. A case study on UK sustainability reporting standards confirms that manufacturing firms are finding direct Power Purchase Agreements (PPAs) with new, local solar or wind farms to be a more robust solution. A PPA demonstrates clear additionality, as your long-term commitment directly enables the financing and construction of a new renewable project. Investing in on-site solar generation is the gold standard, as it provides a perfect geographical and temporal correlation between generation and consumption.
The decision between these options has significant implications for capital expenditure, operational costs, and, most importantly, audit defensibility. An unbundled REC is a simple operating expense but offers little protection from auditor scrutiny or volatile energy prices. A PPA requires no upfront capital but involves a long-term contractual commitment. On-site solar is a capital asset that provides the highest level of compliance and long-term energy cost savings.
The following matrix outlines the key decision criteria for any Compliance Officer weighing these options. It is not merely a financial choice but a strategic one that directly impacts the credibility of your entire ESG report.
| Criteria | Unbundled RECs | Direct Solar PPA | On-site Solar |
|---|---|---|---|
| Capital Requirement | None (OpEx only) | None (long-term contract) | £500k-2M typical |
| SECR Additionality | Low/Rejected | High/Accepted | Highest/Preferred |
| Price Hedging | No protection | 15-25 year fixed | 25+ year savings |
| Balance Sheet Impact | Operating expense | Off-balance sheet | Capital asset |
| Geographic Correlation | Usually fails | Regional match | Perfect match |
The Double-Counting Data Flaw That Triggers Immediate HMRC Fines
One of the most elementary and yet common errors in corporate emissions reporting is double-counting. This occurs when the same emission is reported by two separate entities or by different divisions within the same company. For an auditor, discovering a double-counting error is a clear signal of a weak data governance framework and can trigger a deeper, more painful investigation. A classic example is when both your logistics provider and your company report the emissions for the same delivery (their Scope 1, your Scope 3). Without a clear data boundary, you are both claiming the same tonne of CO2.
This is not a theoretical risk. The Financial Reporting Council has the authority to impose significant penalties for non-compliance with SECR reporting. According to analysis from Net Zero Now, the FRC can impose up to £50,000 in maximum civil penalties for non-compliance. Double-counting is a direct form of non-compliance, representing a material misstatement in your annual accounts. The solution is to establish an ’emissions data ledger’ – a single source of truth that prevents duplication through clear ownership and unique identification.
Implementing such a ledger requires a shift from siloed spreadsheets to an integrated data system. This involves assigning unique identifiers to each emission-generating activity, establishing clear contractual boundaries with suppliers about who reports what, and deploying automated checks to flag potential overlaps. For instance, an API connection between your procurement and logistics departments can automatically cross-reference data to ensure a shipment’s emissions are only counted once. This is not just good practice; it is a fundamental control mechanism required for any financial-grade reporting.
Without these controls, you are not just at risk of a fine; you are misrepresenting your company’s environmental impact to investors, customers, and regulators. The following checklist provides a concrete starting point for building a system that eradicates this critical data flaw.
Action Plan: Emissions Data Ledger Implementation
- Assign unique emission IDs to each activity using blockchain or distributed ledger technology.
- Implement API connections between divisions to flag potential duplicates in real-time.
- Create supplier agreements explicitly defining Scope 1 vs Scope 3 allocation boundaries.
- Deploy automated cross-checking algorithms comparing emissions totals against industry benchmarks.
- Establish quarterly reconciliation processes with all supply chain partners sharing emissions data.
Cutting Logistics Emissions by Redesigning Regional Delivery Routes
Logistics and transport often represent a significant portion of a manufacturer’s Scope 3 emissions. While you may not own the vehicles, you are responsible for reporting the emissions associated with your product distribution. Simply accepting the data provided by your third-party logistics (3PL) provider is insufficient. A proactive approach to compliance involves collaborating with your logistics partners to redesign networks and optimise routes for emission reduction, and then verifying the resulting data.
A highly effective strategy being adopted by UK firms is the move from a centralised distribution model to a regional « hub-and-spoke » system. By establishing smaller micro-hubs closer to final destinations, companies can use larger, more efficient vehicles for the long-haul « trunking » routes and then switch to smaller, often electric, vehicles for last-mile delivery. This approach has proven to dramatically reduce fuel consumption and emissions. Case studies show that UK logistics firms implementing regional micro-hub strategies are achieving a 30-40% reduction in transport emissions by increasing trunking efficiency to near 95% vehicle capacity.
The next layer of sophistication is the use of AI-powered dynamic routing software. Traditional routes are static and fail to account for real-time variables like traffic, weather, or delivery access windows. Dynamic routing algorithms constantly recalculate the most efficient path, reducing mileage, fuel consumption, and, consequently, emissions. The improvements are not marginal. Data shows that AI routing can increase vehicle utilisation by over 30% and reduce emissions per delivery by a similar margin. From an auditor’s perspective, a company that can demonstrate it is using such technology is showing a mature commitment to both reduction and accurate measurement.
Your role as a Compliance Officer is to ensure that these reduction strategies are quantifiable and the data is auditable. This means demanding specific metrics from your logistics partners: average vehicle utilisation, emissions per delivery (in kg CO2e), and daily distance per vehicle. These are the data points that transform a vague « green logistics » initiative into a defensible component of your SECR report.
How to Calculate Scope 3 Emissions Accurately Across Your Entire Supply Chain?
For most manufacturers, the emissions embedded in your supply chain (Scope 3) are the elephant in the room. Data from the UK Green Building Council suggests that for many industries, these indirect emissions account for 80-95% of the total carbon footprint. It is therefore the area of greatest scrutiny and the most difficult to measure. The key to tackling this is to abandon the idea of 100% accuracy from day one and instead adopt a phased, maturity-based model focused on continuous improvement.
The first step, and one that must be completed thoroughly, is supply chain mapping. You cannot measure what you cannot see. This involves using your procurement spend data to map every single supplier and categorising them. The 80/20 rule is a critical tool here: identify the top 20% of your suppliers that are responsible for 80% of your procurement spend. These are your ‘material’ suppliers, and they must be the focus of your primary data collection efforts.
Once you have identified these key partners, you can begin a structured engagement program. This is not a single email asking for ‘their carbon data’. It is a multi-year journey. * Year 1: Focus on education and deploying standardised data collection templates. Explain what data you need (e.g., their energy consumption, fuel usage, raw material inputs) and why. * Year 2-3: Move towards co-investment. For your most strategic suppliers, this could mean helping to fund the installation of sub-metering on their production lines to get the primary, activity-based data you both need. * Year 4-5: The goal is to expand primary data collection to a wider set of suppliers, using automated platforms to manage the data flow and ensure quality. The ultimate objective is to achieve over 90% primary data coverage for all material Scope 3 categories.
This phased approach demonstrates a clear, strategic plan to an auditor. It shows that you understand the complexity of the task and are taking credible, systematic steps to improve data quality over time, rather than relying on crude, indefensible estimates.
Why Over-Provisioned Cloud Servers Secretly Sabotage Your Company’s Carbon Goals?
Your company’s digital infrastructure is a hidden, and rapidly growing, source of Scope 3 emissions. While cloud computing offers efficiency, the common practice of over-provisioning servers—reserving more capacity than is needed « just in case »—leads to significant energy waste. A server that is provisioned but sitting idle still consumes power. From an auditor’s standpoint, this is a material source of emissions that many companies fail to measure or manage, viewing it as a simple IT operational cost.
The solution is a practice known as GreenOps or Sustainable Software Engineering. This involves applying a carbon-aware lens to your cloud architecture and software development lifecycle. For example, a UK technology firm achieved a 40% reduction in cloud-related emissions by implementing simple, automated policies. They used schedulers to automatically shut down non-production development environments outside of business hours and transitioned to « serverless » architectures where computing resources are consumed only when a specific function is executed. This eliminates the problem of the « always-on » idle server.
Another critical, and often overlooked, factor is the geographical location of your cloud servers. The carbon intensity of the electricity grid varies dramatically between regions. Running a server in a region powered predominantly by renewables is significantly less carbon-intensive than running the same server in a region powered by coal. Your cloud provider’s dashboard provides the Carbon-Free Energy (CFE) percentage for each data centre region. Choosing a region with a higher CFE% is a direct and measurable way to reduce your digital carbon footprint, even if it introduces slightly higher latency. An auditor will view a documented policy for region selection based on carbon intensity as a sign of advanced ESG management.
This is not just for technology companies. Any manufacturer using ERP systems, CRM software, or data analytics platforms hosted in the cloud has these emissions in their supply chain. It is your responsibility to query your software vendors and cloud providers on these metrics. Asking for the CFE% of the data centre hosting your ERP system is a legitimate and necessary part of your Scope 3 due diligence.
Key takeaways
- Data integrity is paramount; flawed data is more dangerous than incomplete data as it creates false security and legal exposure.
- Auditors prioritise ‘additionality’ and ‘granularity’. Generic certificates and facility-wide averages are no longer sufficient proof.
- A systematic, tiered approach to data collection across all scopes is the only method that can withstand regulatory scrutiny.
Streamlining ESG Reporting Requirements for UK Mid-Market Manufacturers
The landscape of environmental reporting is complex and fragmented. For many UK manufacturers, the administrative burden of complying with multiple frameworks—SECR, ESOS, and the emerging TCFD recommendations—can be overwhelming. This complexity often leads to siloed efforts, data inconsistencies, and duplicated work, increasing both cost and the risk of error. According to IBM, SECR reporting requirements apply to an estimated 11,900 organisations across the UK, and this number is only set to grow.
The most effective strategy to manage this burden is to harmonise your data collection and reporting cycles. Instead of treating SECR, ESOS, and other ESG disclosures as separate projects, they should be viewed as different outputs from a single, unified data-gathering process. The data required for your energy consumption under SECR is the same data needed for your ESOS audit. The climate risks you identify for TCFD are directly informed by the emissions data you gather for SECR.
A successful approach, as evidenced by leading UK manufacturers, is to establish a central « ESG data hub ». This can be a dedicated software platform or a robust internal process managed by a cross-functional team. This hub becomes the single source of truth for all energy, carbon, and other sustainability metrics. Data is collected once, validated rigorously, and then used to populate the various report formats as required. A UK manufacturer that consolidated its reporting into a single quarterly data collection cycle was able to reduce the associated reporting effort by a staggering 60%, while simultaneously improving data quality scores from its external auditors.
This streamlined approach offers multiple benefits. It dramatically reduces the administrative workload on your compliance and finance teams. It ensures consistency across all public disclosures, reducing the risk of contradictory statements that could attract regulatory attention. Most importantly, it shifts the focus from chasing data for compliance deadlines to using that data for strategic decision-making to actually reduce emissions and mitigate climate risk.
Your company’s compliance with UK emissions reporting law is not a project to be completed, but a continuous process of data governance to be maintained. The first and most critical step is to conduct an unflinching audit of your current data collection methodologies against the principles of granularity, verifiability, and additionality. Begin today by auditing your supplier data framework; the integrity of your entire report depends on it.