Manual ESG reporting is no longer just inefficient; for UK manufacturers, it’s a direct threat to your capital access, regulatory standing, and market competitiveness.
- Inaccurate Scope 3 data, often stemming from unverified supplier estimates, can invalidate your entire sustainability report during an audit.
- Vague environmental claims based on spreadsheet data invite severe greenwashing penalties from the CMA and HMRC.
Recommendation: The only defensible strategy is to transition from disparate spreadsheets to a centralised, automated ESG data platform that ensures an auditable, single source of truth for all disclosures.
For CEOs and Compliance Officers in the UK’s manufacturing sector, the demand for transparent Environmental, Social, and Governance (ESG) data is no longer a distant concern. It has become an immediate and high-stakes operational reality. The pressure from investors, lenders, and regulators for verifiable sustainability metrics has intensified, moving far beyond a simple marketing exercise. Yet, many firms continue to approach this critical function with outdated tools, relying on a patchwork of manual spreadsheets and departmental estimates to compile their disclosures.
This approach fundamentally misunderstands the current landscape. It frames ESG as a peripheral reporting task rather than a core business discipline, equivalent in importance to financial accounting or quality control. The platitudes about « improving brand image » miss the most pressing dangers: poor data integrity doesn’t just tarnish a company’s reputation; it actively restricts access to capital markets, creates significant legal exposure, and leaves the business vulnerable to severe regulatory penalties.
The true challenge lies not in the *ambition* to be sustainable, but in the *discipline* of proving it with robust, auditable data. This is where the risk resides and where the strategic advantage can be won. The shift from manual, error-prone data collection to automated, verifiable systems is not merely an efficiency upgrade; it is a necessary evolution to survive and thrive in a market that now demands proof, not just promises.
This guide deconstructs the most significant ESG risks facing UK manufacturers today. We will examine how data quality directly impacts access to finance, the complexities of calculating supply chain emissions, the critical choice of reporting frameworks, and the severe consequences of unintentional greenwashing. The following sections provide a clear roadmap for transforming compliance from a costly burden into an automated, auditable, and ultimately competitive advantage.
Summary: Streamlining UK ESG Reporting: From Regulatory Burden to Competitive Advantage for Manufacturers
- Why Delaying Sustainability Disclosures Will Restrict Your Access to Bank Capital?
- How to Calculate Scope 3 Emissions Accurately Across Your Entire Supply Chain?
- SASB vs TCFD Frameworks: Which Aligns Best With British Regulatory Standards?
- The Greenwashing Mistake That Invites Severe HMRC and CMA Penalties
- Automating Energy Consumption Data Collection Across Multiple Factory Sites
- Why Relying on Supplier Estimates Invalidates Your Mandatory Scope 3 Reports?
- Why Over-Provisioned Cloud Servers Secretly Sabotage Your Company’s Carbon Goals?
- Tracking and Reducing Industrial Emissions for UK Regulatory Compliance
Why Delaying Sustainability Disclosures Will Restrict Your Access to Bank Capital?
In the current financial climate, access to capital is increasingly tied to a company’s demonstrated commitment to sustainability. Banks and institutional investors are no longer simply reviewing financial statements; they are conducting deep ESG due diligence to assess long-term risk. For a mid-market manufacturer, a weak, delayed, or non-existent sustainability report is now a major red flag, signalling poor risk management and a lack of operational foresight. This perception directly translates into more restrictive lending terms, higher interest rates, or even outright loan refusal.
Financial institutions are systematically integrating ESG metrics into their credit risk models. They understand that companies with poor environmental performance are more exposed to regulatory fines, supply chain disruptions, and shifting consumer preferences. Consequently, a manufacturer unable to provide clear, verifiable data on its energy consumption, waste management, or supply chain emissions is considered a higher-risk investment. The era of securing capital based on financial performance alone is over. ESG performance is now a key determinant of a company’s ‘bankability’, a reality supported by the fact that many UK firms now see mandatory reporting as a driver of innovation and competitiveness.
Proactive manufacturers are turning this requirement into an opportunity by pursuing Sustainability-Linked Loans (SLLs). These financial instruments offer tangible benefits, such as interest rate reductions, for achieving pre-agreed ESG targets. However, accessing these loans requires a robust data infrastructure from the outset. Lenders demand verified baseline data and a clear, auditable system for tracking progress against key performance indicators (KPIs). Without an automated data management system, a company cannot provide the level of assurance required, effectively locking itself out of this growing pool of favourable capital.
How to Calculate Scope 3 Emissions Accurately Across Your Entire Supply Chain?
For most manufacturers, the greatest environmental impact—and the most significant reporting challenge—lies outside their factory walls. Scope 3 emissions, which encompass all indirect emissions from a company’s value chain, are a critical focus for UK regulators. This includes everything from the raw materials you purchase to the downstream transportation of your finished products. The difficulty is that this data is not under your direct control; it resides with hundreds or even thousands of suppliers, each with varying levels of sophistication in their own data tracking.
The scale of this challenge cannot be overstated. For many industrial producers, 80-95% of the total carbon footprint comes from Scope 3 activities. Relying on simple spend-based estimates—calculating emissions based on how much you spend with a supplier—is a common starting point, but it is increasingly seen as insufficient by auditors and regulators for material parts of your supply chain. It lacks the granularity needed for accurate reporting and, more importantly, for identifying targeted opportunities for reduction.
As the visualised network above suggests, tracking these emissions requires a systematic approach to data flow. The goal is to move beyond broad estimates and toward collecting more precise data, at least from your most significant suppliers. This involves engaging them directly, providing them with tools or platforms to report their emissions data, and establishing a centralised system to aggregate and analyse this information. Without this, your Scope 3 disclosure remains a high-level guess, undermining the credibility of your entire ESG report.
Case Study: UK SME Scope 3 Reporting Challenges
Research on four UK-based manufacturing SMEs highlighted the common struggle with Scope 3 data collection due to limited resources and influence over large suppliers. The study revealed a pragmatic, two-tiered approach: the firms used spend-based calculation methods for the majority of their smaller suppliers to establish a baseline, while simultaneously launching targeted engagement campaigns to obtain higher-quality, primary data from their top 20% strategic suppliers who constituted the bulk of their value chain emissions.
SASB vs TCFD Frameworks: Which Aligns Best With British Regulatory Standards?
Navigating the « alphabet soup » of ESG frameworks can be daunting, but for UK manufacturers, the choice is becoming clearer. The two most prominent frameworks are the Task Force on Climate-related Financial Disclosures (TCFD) and the Sustainability Accounting Standards Board (SASB). Understanding their distinct focus is crucial for efficient and compliant reporting. The TCFD is primarily concerned with climate-related financial risks and opportunities. It requires companies to disclose how climate change could impact their business strategy, governance, and financial planning. In the UK, reporting aligned with TCFD recommendations is already mandatory for the largest companies.
SASB, on the other hand, takes an industry-specific approach. It identifies the ESG topics that are most financially material for companies in a particular sector. For a manufacturer, this could include topics like water usage, employee health and safety, and supply chain management, in addition to climate issues. While SASB has historically been voluntary, its standards have been incorporated into the new global baseline set by the International Sustainability Standards Board (ISSB). The UK government has signalled its intention to adopt these ISSB standards, likely making SASB’s industry-specific metrics a future requirement.
As the ICAEW Corporate Reporting Faculty notes in their TCFD and Related UK Reporting Regulations Guide:
The UK government has indicated an intention to align with international standards in the future, expressing a preference for climate reporting to be prepared in accordance with a global, consistent framework.
– ICAEW Corporate Reporting Faculty, TCFD and Related UK Reporting Regulations Guide
Therefore, the question is not « TCFD or SASB? » but rather « how to prepare for both? » A best-practice approach involves using TCFD as the framework for climate risk disclosure and incorporating SASB’s industry-specific metrics to provide a more holistic and financially material ESG report. This combined strategy not only satisfies current UK regulations but also prepares your company for the imminent adoption of the comprehensive ISSB standards.
This comparative table clarifies the current status and focus of each framework for UK manufacturers.
| Framework | UK Regulatory Status | Focus Area | Implementation Timeline |
|---|---|---|---|
| TCFD | Mandatory for large companies (500+ employees, £500m+ turnover) | Climate-related financial risks | In effect since April 2022 |
| SASB | Voluntary, incorporated into ISSB standards | Industry-specific material topics | Expected UK adoption 2026 |
| Combined Approach | Best practice for ISSB readiness | Comprehensive ESG disclosure | Prepare now for 2026 requirements |
The Greenwashing Mistake That Invites Severe HMRC and CMA Penalties
Greenwashing is no longer a vague reputational risk; it is a serious compliance threat with significant financial consequences. For UK manufacturers, the most dangerous form of greenwashing is often unintentional, stemming not from malice but from poor data management. When a company makes an environmental claim—such as « 30% reduction in waste » or « 50% recycled content »—that cannot be substantiated with robust, auditable data, it exposes itself to severe penalties from regulators like the Competition and Markets Authority (CMA) and HMRC.
The core of the problem lies in the continued reliance on manual processes. When data is scattered across disparate spreadsheets, managed by different departments, and based on a mix of actual measurements and rough estimates, the potential for error and inconsistency is enormous. According to survey data, an alarming 50% of UK businesses still rely on manual spreadsheets for their ESG disclosures. This practice creates what is known as ‘Shadow ESG’—where the figures used in marketing materials may not match the audited figures in official reports, creating a direct compliance breach.
The CMA’s Green Claims Code is explicit: all environmental claims must be truthful, accurate, and fully substantiated. A claim based on an unverified estimate from a spreadsheet is not considered substantiation. If a company is found to have made misleading claims, the CMA has the power to impose significant fines and mandate public corrections. Furthermore, inaccurate carbon reporting can lead to issues with HMRC regarding climate-related levies and taxes. The only effective defence is a single source of truth—a centralised data management system that ensures every public claim is directly traceable to verified, auditable data.
Your Action Plan: Avoiding Greenwashing Penalties
- Ensure all ESG claims are backed by third-party verified data, not estimates.
- Implement centralised ESG data management to prevent ‘Shadow ESG’ reporting inconsistencies.
- Cross-check all marketing materials against official audited ESG reports before publication.
- Document the methodology and limitations of all environmental claims clearly.
- Establish board-level oversight of all public-facing sustainability communications.
Automating Energy Consumption Data Collection Across Multiple Factory Sites
For any manufacturer with more than one facility, collecting accurate energy consumption data is a logistical and administrative challenge. Manually gathering utility bills, reading meters, and consolidating this information into a central spreadsheet is not only time-consuming but also riddled with potential for human error. Delays in receiving data from one site can hold up the entire reporting process, while transcription errors can skew the final figures, undermining the credibility of your Scope 1 and Scope 2 emissions calculations.
This manual approach is simply not scalable or defensible in the current regulatory environment. The solution lies in automation. By deploying Internet of Things (IoT) sensors and smart meters across factory sites, companies can establish a system for real-time, automated data collection. These devices can monitor electricity, gas, and water usage continuously and feed the data directly into a central ESG platform. This eliminates manual data entry, reduces the risk of errors, and provides a continuous, granular view of energy performance.
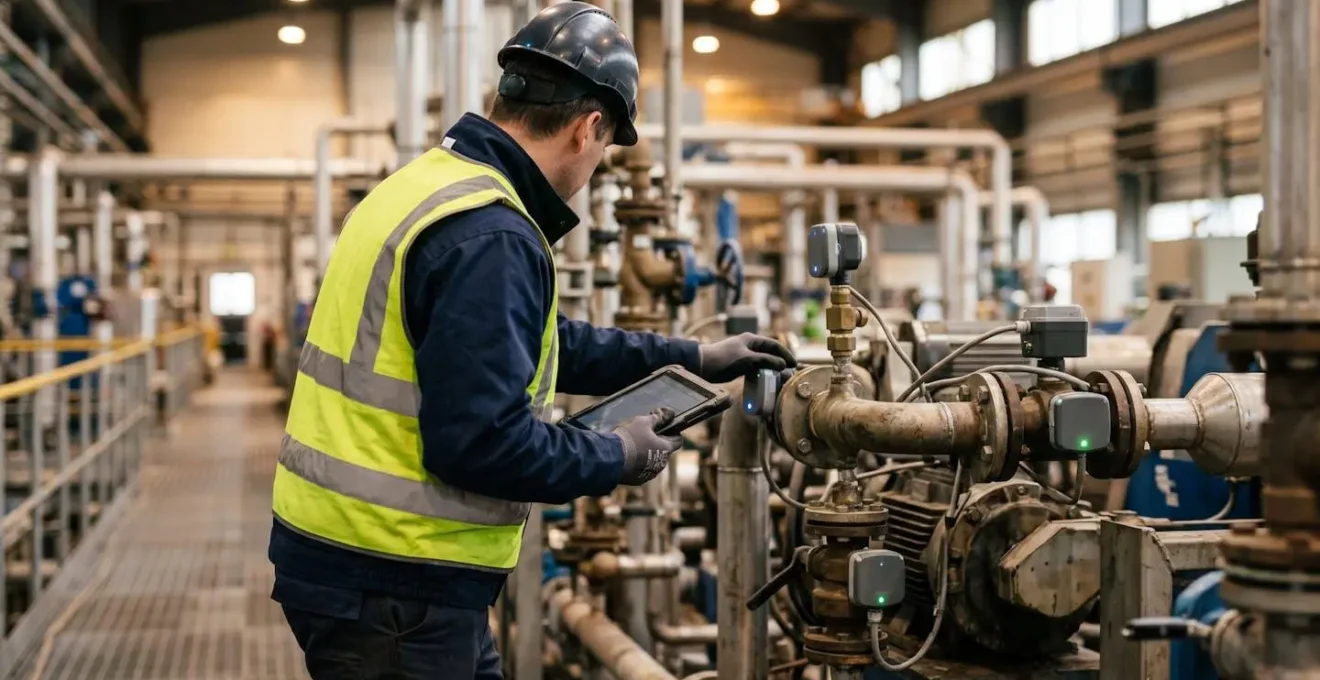
This automated approach transforms energy management from a reactive, historical reporting exercise into a proactive, strategic function. With real-time data, site managers can identify anomalies, detect equipment inefficiencies, and implement targeted energy-saving initiatives with measurable results. As the UK Government Digital Sustainability Alliance working group has emphasised, the focus should be on the practical measurement of material impacts. Automating the collection of your most significant energy data is the most pragmatic and effective first step. It builds a solid, auditable foundation for your entire ESG report and provides the actionable insights needed to drive genuine performance improvements, not just report on them.
Why Relying on Supplier Estimates Invalidates Your Mandatory Scope 3 Reports?
One of the most critical—and commonly misunderstood—aspects of Scope 3 reporting is the requirement for data quality. While regulators acknowledge the challenges of collecting data from a vast supply chain, there is a clear line between an acceptable proxy and an indefensible guess. Relying on unverified, informal estimates from your suppliers for a material portion of your emissions is a practice that will not withstand auditor scrutiny. Using a verbal assurance from a sales representative or a generic figure from a supplier’s marketing brochure is not a valid data point.
Auditors are tasked with providing assurance on your ESG disclosures. If the data underpinning a significant part of your report—such as your main Scope 3 categories—is not traceable, verifiable, or based on a reasonable methodology, they cannot sign off on it. Instead, they will be forced to issue a ‘qualified opinion’ or, in severe cases, a ‘disclaimer of opinion’. Such a finding renders your entire sustainability report effectively useless. It signals to investors, lenders, and regulators that your company’s disclosures are unreliable.
This point is explicitly reinforced by regulatory bodies. In the UK Government’s Call for Evidence on Scope 3 emissions, it is made clear that data quality is paramount. As stated in the official documentation:
Using unverified supplier estimates for a material part of your Scope 3 emissions will result in a ‘qualified opinion’ or ‘disclaimer of opinion’ from the auditor, rendering the report useless for investors and regulators.
– UK Government Call for Evidence, Scope 3 Emissions in the UK Reporting Landscape
This is not a minor compliance issue; it strikes at the heart of your report’s credibility. The solution is a tiered approach. For smaller, non-strategic suppliers, using industry-average emission factors (e.g., from databases like DEFRA) is an acceptable and defensible proxy. However, for your top strategic suppliers that constitute the bulk of your supply chain emissions, you must actively work to obtain primary data or data based on a documented methodology. A system that can manage these different data types and document their sources is essential for creating an auditable and defensible Scope 3 report.
Why Over-Provisioned Cloud Servers Secretly Sabotage Your Company’s Carbon Goals?
In the drive to digitise operations and implement new software—including ESG reporting platforms—many companies overlook a significant and growing source of their own carbon footprint: their IT infrastructure. The emissions associated with data centres and cloud computing fall under a company’s Scope 3 emissions (or Scope 2 if the cloud provider’s electricity is considered a direct purchase). A common but wasteful practice known as ‘cloud over-provisioning’ can secretly undermine a manufacturer’s sustainability goals.
Over-provisioning occurs when companies reserve more cloud server capacity than they actually need, often ‘just in case’ of a spike in demand. These servers run continuously, consuming electricity and generating carbon emissions, even when they are sitting idle. This inefficiency is far from trivial; technical assessments indicate that over-provisioning servers by just 30% can add tonnes of CO2e to a company’s annual carbon footprint. For a manufacturer investing heavily in reducing factory emissions, ignoring this digital waste is a critical oversight.
A ‘Green IT’ strategy is therefore an essential component of a holistic ESG program. This involves several key actions. First, auditing your current cloud infrastructure to identify and decommission idle or underutilised resources. Second, adopting more efficient architectures, such as serverless computing, which automatically scale resources up or down (even to zero) based on real-time demand, ensuring you only pay for—and generate emissions from—what you use. Finally, it involves selecting cloud providers that are themselves committed to sustainability, offering ‘green regions’ powered by renewable energy and providing tools to calculate the carbon footprint of your IT workload.
Integrating your digital carbon footprint into your sustainability reporting demonstrates a sophisticated understanding of your company’s total environmental impact. It shows stakeholders that you are looking beyond the factory floor and taking responsibility for every aspect of your operational footprint.
Key Takeaways
- The quality and verifiability of your ESG data now directly impact your ability to secure bank loans and investment capital on favourable terms.
- Scope 3 emissions are non-negotiable and require a systematic approach to data collection, moving beyond simple estimates for all material suppliers.
- Automation is the only viable long-term strategy to mitigate greenwashing risks, ensure data integrity, and create an auditable trail for regulators.
Tracking and Reducing Industrial Emissions for UK Regulatory Compliance
For UK manufacturers, ESG reporting has moved decisively from a voluntary activity to a complex web of mandatory regulations. A failure to comply is not an option and carries significant legal and financial risk. The regulatory landscape requires companies to have a robust system for tracking, managing, and reporting emissions and other sustainability data. Key regulations include the Streamlined Energy and Carbon Reporting (SECR) framework, which requires large companies to report their UK energy use and associated Scope 1 and 2 emissions.
More recently, the UK has made TCFD-aligned climate reporting mandatory for its largest entities. According to government estimates, over 1,300 of the largest UK-registered companies and financial institutions must now disclose climate-related financial risks. Looking ahead, the UK is set to adopt the IFRS Sustainability Disclosure Standards (which build on TCFD and SASB), creating the UK Sustainability Disclosure Standards (SRS). This will bring even greater standardisation and broader requirements, including more rigorous Scope 3 reporting, expected from 2026 onwards.
This evolving regulatory pressure makes one thing clear: manual, spreadsheet-based systems are no longer fit for purpose. They cannot provide the granularity, consistency, and auditability required to meet these diverse and stringent requirements. A modern manufacturing operation needs a dedicated ESG platform that can act as a central hub, automatically collecting data from various sources—from factory floor sensors to supplier portals and utility providers. Such a system ensures that the data is consistent, up-to-date, and readily available for audits and disclosures.
Embracing this technology is not just about compliance; it’s about control. It provides the detailed insights necessary to identify inefficiencies, model reduction scenarios, and track progress against targets. It transforms reporting from a reactive, year-end scramble into a continuous, data-driven management process, turning a regulatory obligation into a strategic tool for operational excellence and long-term value creation.
The era of treating ESG as an afterthought managed with disparate spreadsheets is definitively over. To protect your access to capital, ensure regulatory compliance, and maintain a competitive edge, the next logical step is to evaluate an automated ESG data platform. This provides the single source of truth and the complete, auditable trail required to confidently face investors, regulators, and the market.
Frequently Asked Questions on Streamlining ESG Reporting Requirements for UK Mid-Market Manufacturers
What’s the difference between acceptable estimates and invalid estimates?
Industry-average emission factors (which act as valid proxies) from recognised sources like DEFRA are generally acceptable for calculating emissions from small, non-strategic suppliers. However, informal or verbal estimates provided by a supplier’s sales representative, without any supporting methodology, are not defensible for material suppliers and will likely be rejected during an audit.
When is primary data absolutely required vs optional?
Primary data (i.e., data directly from the source, such as a supplier’s actual energy usage) is considered non-negotiable for your top strategic suppliers—typically the 20% of suppliers that constitute 80% of your supply chain emissions. For the long tail of smaller, low-impact suppliers, using secondary data (like industry-average emission factors) is an acceptable and practical approach.
How do auditors evaluate Scope 3 data reliability?
Auditors assess the quality of Scope 3 data across four key dimensions: accessibility (can the data be obtained?), completeness (does it cover the required scope?), accuracy (is the data free from material error?), and timeliness (is the data from the correct reporting period?). Having a well-documented methodology for how data was collected, calculated, and where proxies were used is absolutely critical for passing this evaluation and receiving a clean assurance opinion.